What is the CSRD? Corporate Sustainability Reporting Directive explained


CSRD definition: origins and background of the directive
With the introduction of the NFRD (Non-Financial Reporting Directive) in 2014, the European Union took an important step toward greater transparency on environmental, social, and governance (ESG) aspects within companies. The goal was to give investors and other stakeholders better insight into the non-financial risks and impacts of corporate activities.
To support the goals of the European Green Deal from 2019, in particular reducing net greenhouse gas emissions in the EU by at least 55% by 2030 compared to 1990 and reaching net zero by 2050, the regulatory framework for sustainability reporting was significantly expanded. A central part of this development is the Corporate Sustainability Reporting Directive (CSRD).
The CSRD is designed to close existing gaps in the NFRD and enable clearly standardized, comparable, and verifiable sustainability reporting.
What is the CSRD?
The CSRD sets out which sustainability information companies must report and how this information should be structured and disclosed. Reporting is based on the European Sustainability Reporting Standards, which were adopted in July 2023. These standards define uniform requirements for disclosing environmental, social, and governance information. The CSRD changes both the scope of the reporting obligation and the depth and standardization of reporting compared to the previous NFRD.
The introduction of the CSRD represents a significant step toward corporate accountability and transparency in carbon accounting, as it requires key European economic actors and CO₂ emitters to provide detailed and traceable emissions information at the company level. Beyond this, the CSRD requires transparency across nine other environmental, social, and governance areas.
Why was the CSRD introduced?
Providing transparent sustainability information is of great importance to affected companies. The EU Taxonomy, which is closely linked to the CSRD, creates a direct connection to financial reporting by assessing revenue, CapEx, and OpEx based on sustainability criteria. This gives investors and other stakeholders a better basis for assessing a company’s sustainability performance and making informed investment decisions.
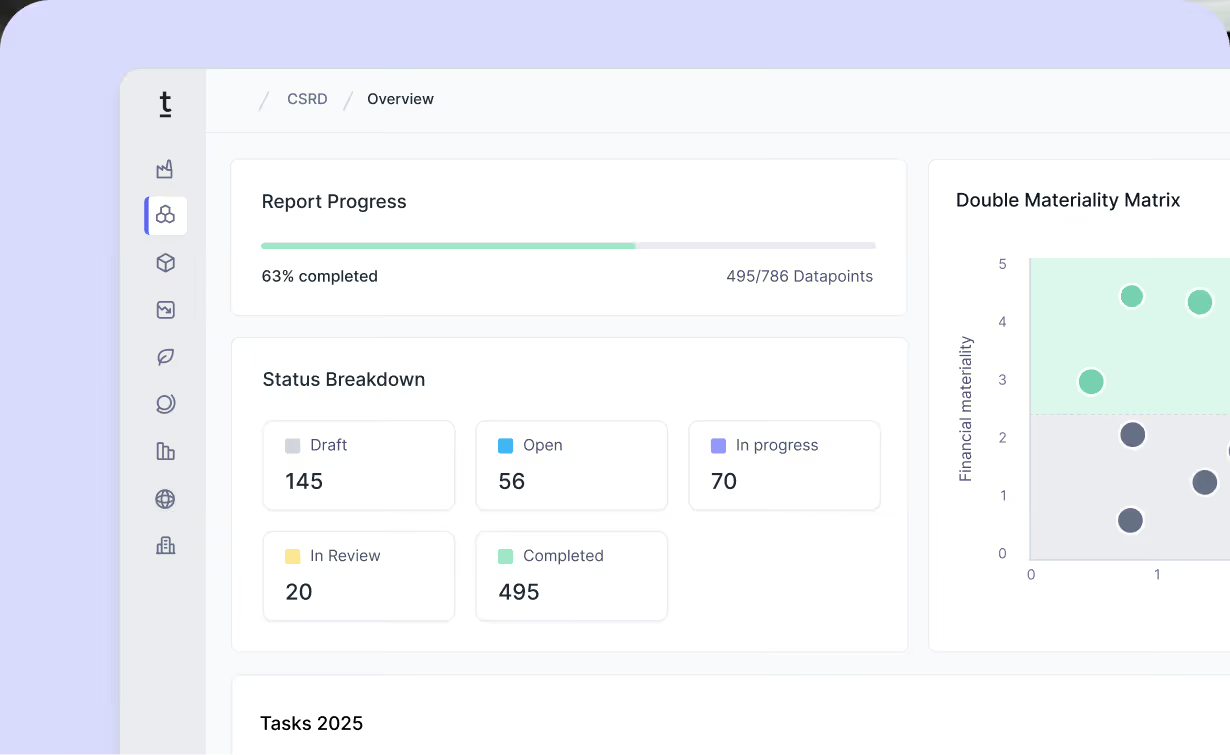
Which sustainability aspects actually need to be reported is determined as part of the double materiality assessment under the CSRD. It considers both financial materiality and a company’s impacts on the environment and society. This enables companies to identify their material sustainability topics and focus their reporting efforts on the information that is relevant.
Which companies are affected by the CSRD?
The EU Sustainability Omnibus I package adjusted the scope of the CSRD.
Directly affected
Under the current legal framework, companies are required to report if they meet both criteria: more than 1,000 employees and more than €450 million in revenue. The reporting obligation is being phased in, and individual deadlines have additionally been pushed back by two years under the Stop-the-Clock Directive.
Indirectly affected
The CSRD sets off a "snowball effect" that must be taken into account when determining the scope of affected companies. For example, original equipment manufacturers (OEMs) may be directly required to disclose information on their supply chain emissions. This can mean that companies not yet subject to reporting obligations themselves must still provide sustainability indicators such as the Product Carbon Footprint (PCF) or energy mix data to their business customers. This interconnected reporting structure means that disclosure requirements cascade along the supply chain, ultimately contributing to a more comprehensive understanding of CO₂ emissions and sustainability performance.
CSRD reporting: process and requirements
Companies subject to the CSRD must publish their sustainability information as part of the management report within their annual report. Reporting takes place:
- according to the European Sustainability Reporting Standards (ESRS)
- in a standardized digital format
- with mandatory external assurance (audit), currently with limited assurance
A central principle is double materiality. Companies only report on topics identified as material through this assessment. If climate change is assessed as a material topic (which is common), Scope 3 emissions also play an important role in reporting. These cover indirect emissions along the entire value chain, for example from purchased materials, business travel, logistics, or the use and disposal of products.
Consequences of non-compliance with the CSRD
- Sanctions and PenaltiesSetting sanctions is the responsibility of individual EU member states. Germany is currently still drafting its CSRD implementation law (German-language source), expected sometime in 2026. Under current German law, companies can be penalized for false or incomplete reports with fines or up to three years' imprisonment under Section 331 (1) No. 1 and 2 of the German Commercial Code (HGB). Fines may also be imposed under Section 334 (1) No. 3 and 4 HGB.
- Reputational DamageViolating the CSRD can lead to loss of trust and significant reputational damage, with long-term business consequences.
- Companies that fail to meet sustainability standards risk losing customers and investors. This can lead to revenue losses and a weaker competitive position. In addition, non-compliance with CSRD reporting obligations (Section 289 et seq. HGB) can, under public procurement law, result in a company being excluded from public tenders.
How to prepare for CSRD requirements
Many mid-sized industrial companies face major challenges when implementing CSRD requirements. Even if a company is not directly subject to reporting obligations, requirements can still arise from supply chains, ESG ratings, banks, or investors. It is therefore worthwhile to start collecting and structuring sustainability data early. Given the complexity of the requirements, using suitable software can provide valuable support.
Frequently asked questions about CSRD
Does CSRD apply to my company even if I'm not directly required to report?
Yes, indirectly. Through this "snowball effect," companies with direct CSRD reporting obligations often ask their suppliers for sustainability data, such as the Product Carbon Footprint, even if those suppliers aren't themselves in scope of CSRD.
Does CSRD reporting need to be audited?
Yes, external assurance is mandatory, currently at the "limited assurance" level.
What penalties apply for CSRD violations in Germany?
Under current law, false or incomplete reports can result in fines or up to three years' imprisonment under Section 331 of the German Commercial Code (HGB), along with fines under Section 334 HGB. Germany's CSRD implementation law, which will set the final penalties, is expected in 2026.
What's the difference between CSRD and the previous NFRD?
CSRD significantly expands the number of companies required to report, mandates external assurance, and, with the ESRS, introduces standardized reporting requirements for the first time — the NFRD gave companies far more flexibility.
What does double materiality mean under CSRD?
Companies assess both the financial materiality of a topic and its impact on the environment and society. Only topics classified as material need to be reported — learn more in our guide to the double materiality assessment.
How are CSRD and the EU Taxonomy connected?
The EU Taxonomy complements CSRD by evaluating revenue, CapEx, and OpEx against sustainability criteria, creating a direct link to financial reporting.
Does my industrial company need CSRD software?
Given the complexity of the requirements, from data collection to ESRS structuring to audit-proof documentation, CSRD software is a valuable asset for most industrial companies, especially those managing multiple sites, supply chains, or reporting standards at once.
How does Tanso support CSRD reporting?
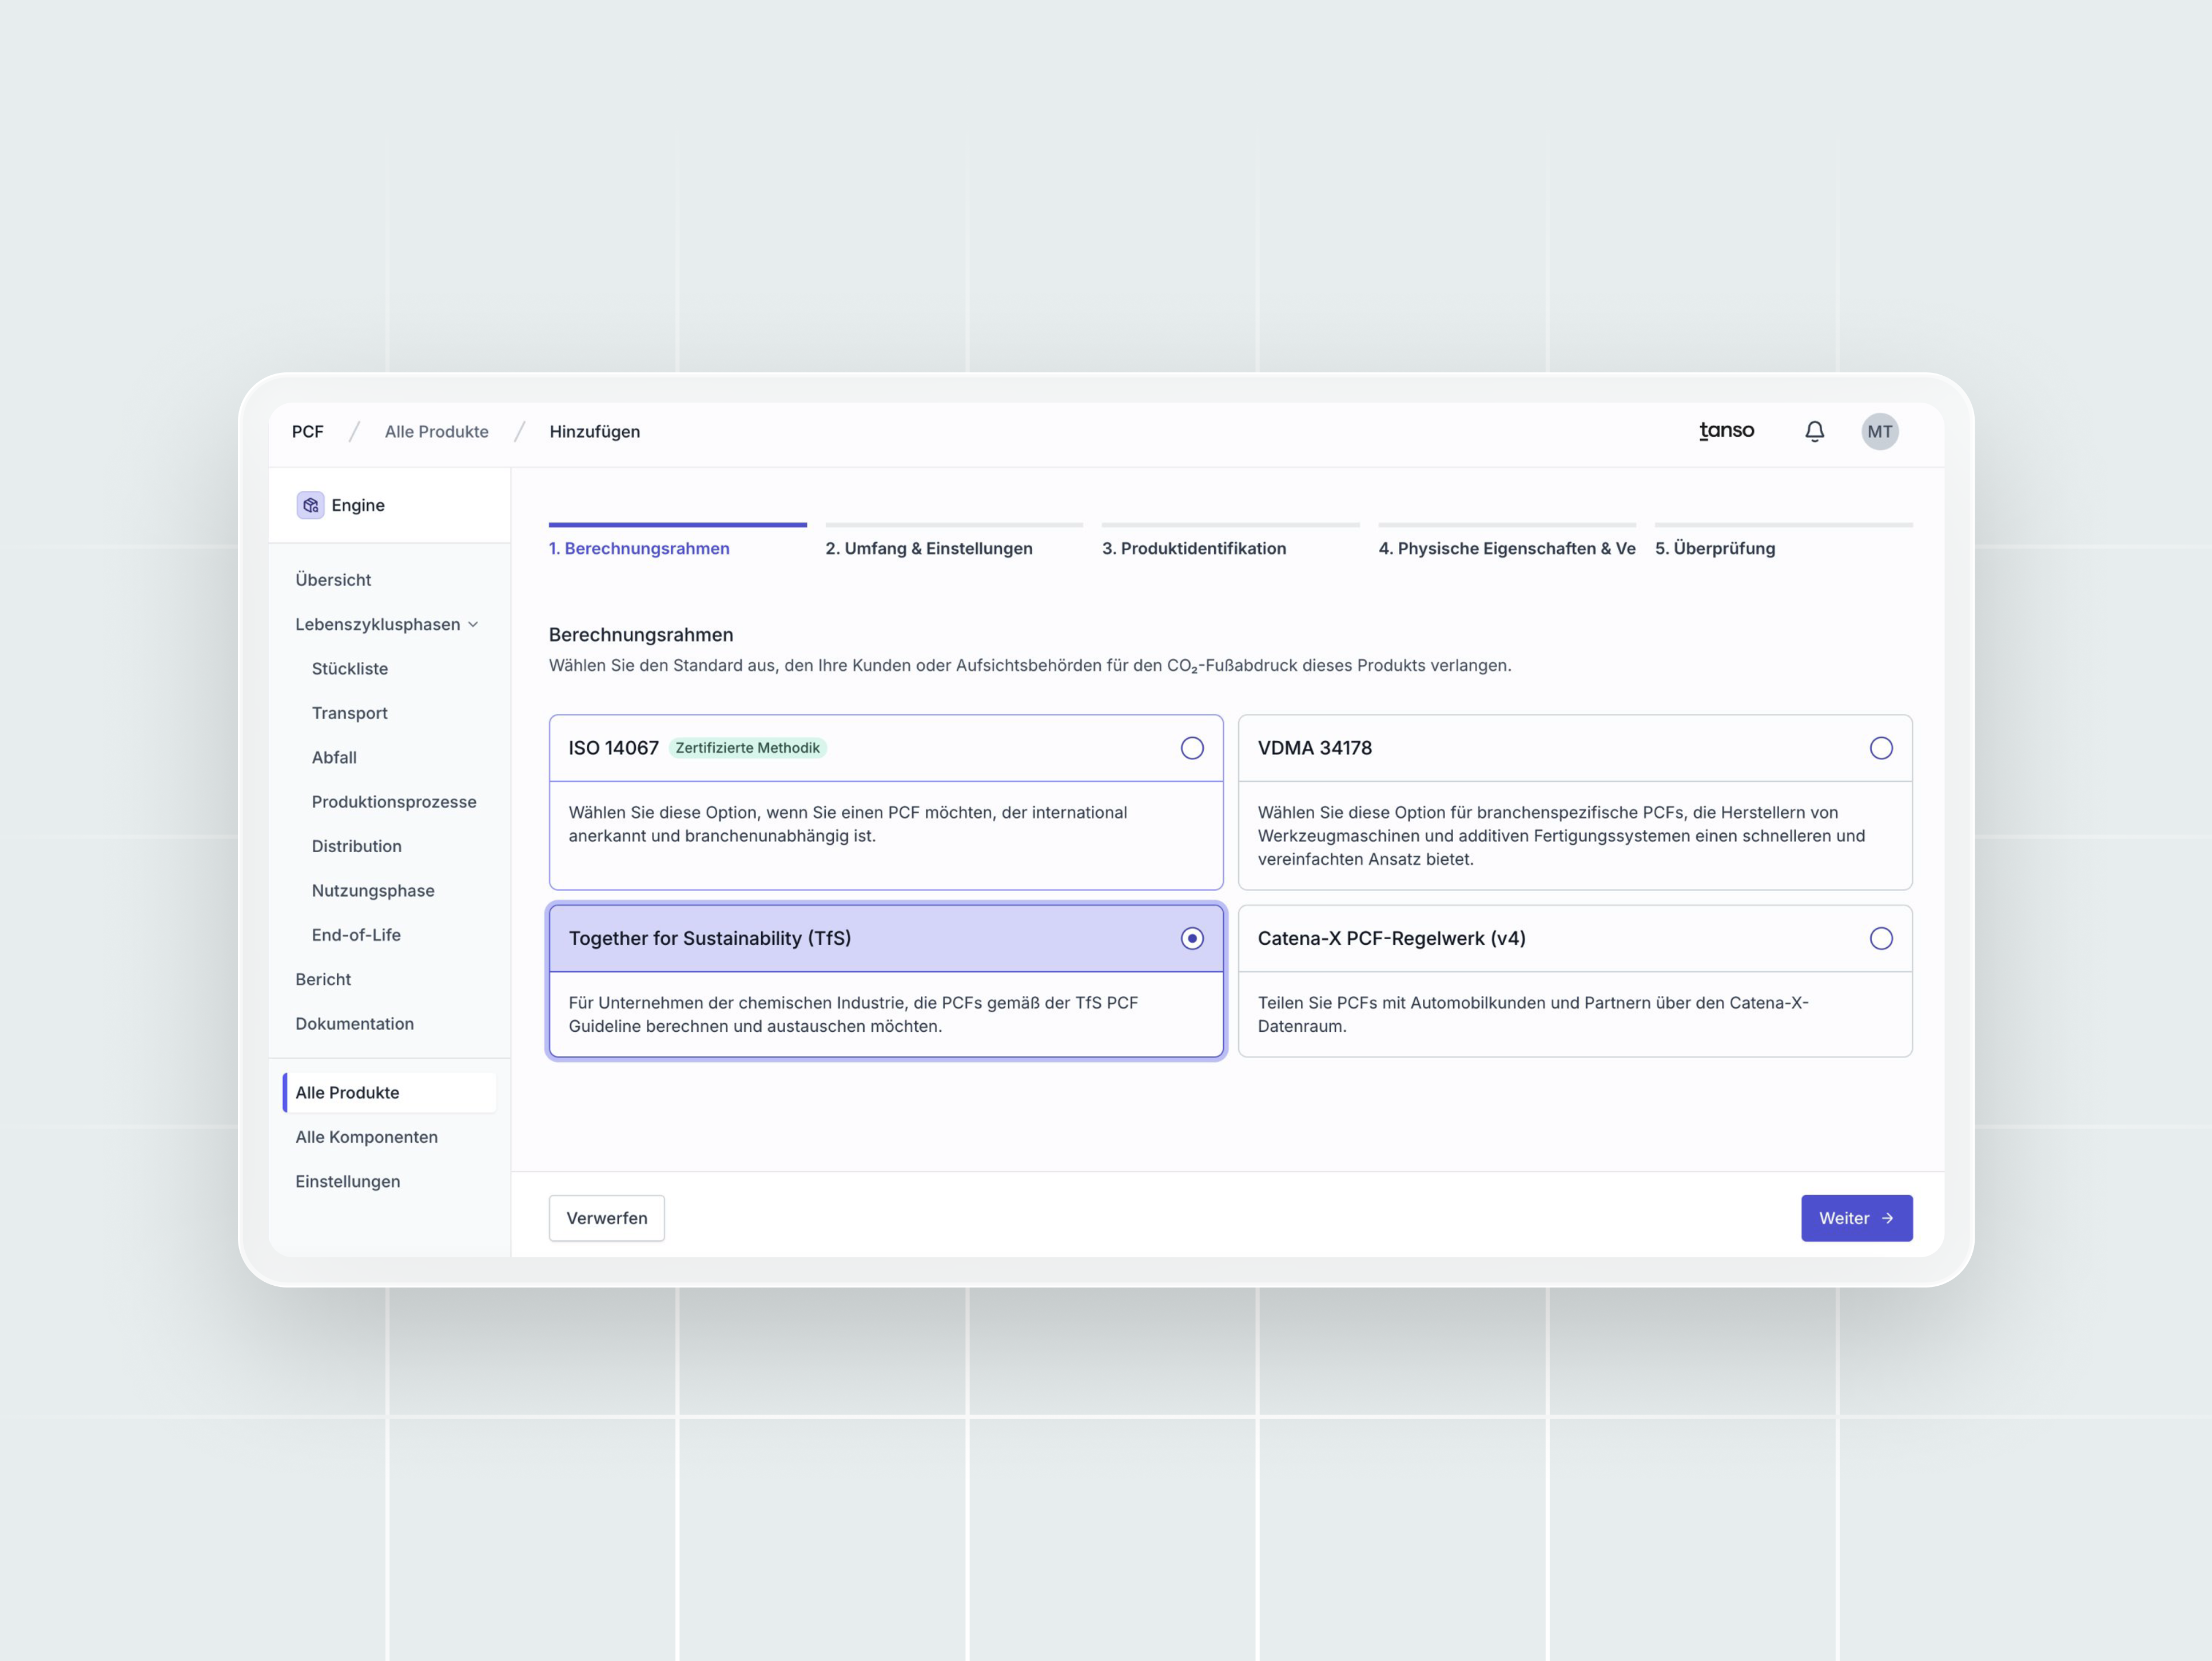
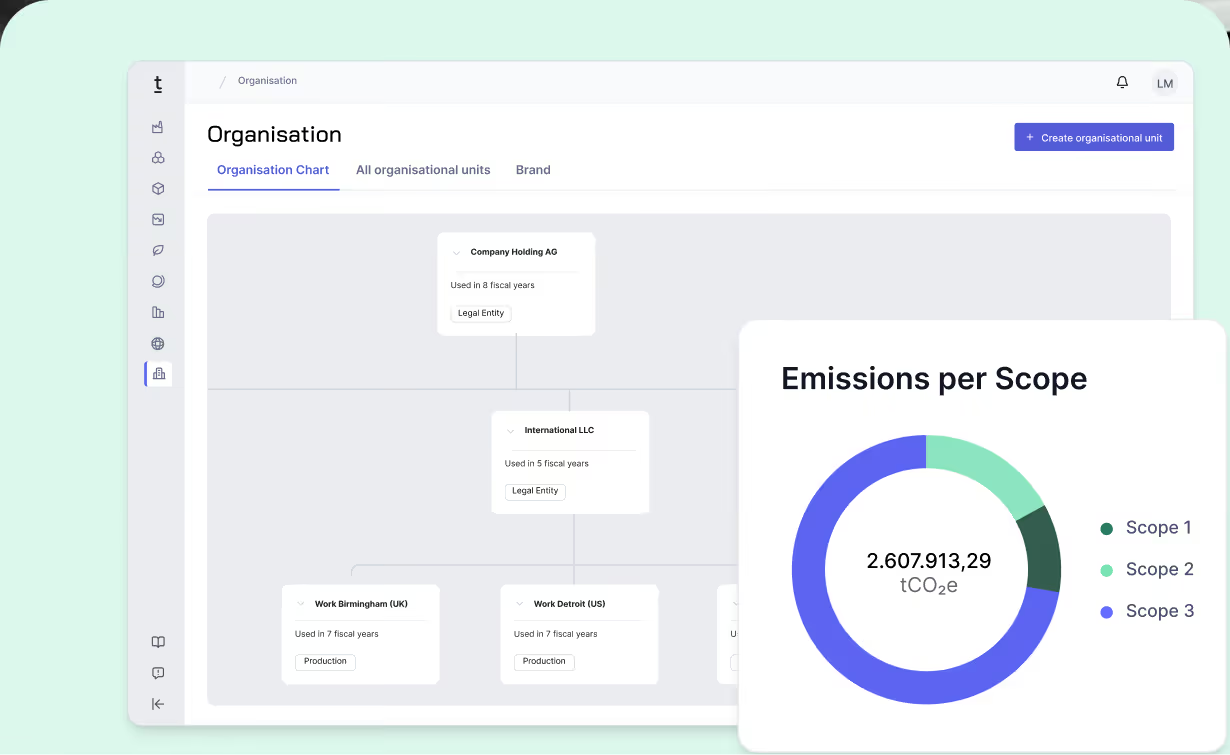
With the Tanso software, you capture CCF, PCF, and social KPIs consistently in one central data source, and carry out your double materiality assessment and ESRS requirements in a structured, audit-proof way. The platform also enables flexible multi-reporting across ESRS, EcoVadis, SAQ 5, GRI, CDP, and VS(ME), so you can manage regulatory requirements as part of your overall sustainability strategy rather than in isolation.